

Remodeling Contractor Insurance That Helps Protect Your Business.
We don't just find you the lowest price — we build a policy that holds up when you need it most. Our agents compare options across 20+ top-rated carriers to find you the right coverage at the best value.
THE FIRSTMARK CHALLENGE
A better way to review coverage.
Four simple steps. Zero obligation.

Have A Conversation.

We shop the markets.

Review the results.

You decide.
- Licensed in 39 states
- 20+ Insurance Carriers
- Headquartered in Edmonds, WA
- Independent & Unbiased
A better way to review coverage.
The Firstmark Challenge
Our simple, guided process makes reviewing your insurance easy. We take the time to understand your needs, compare options across top carriers, and present clear results—so you can make a confident decision.
01
Have A Conversation
02
We Shop The Markets
03
Review The Results
04
You Decide!
Build, Renovate & Remodel With Confidence
With FirstMark Insurance’s dedicated commercial insurance team, you get experienced agents comparing coverage from over 20 insurance carriers to help protect your remodeling business, employees, vehicles, tools, equipment, and operations—with strong coverage and competitive pricing.
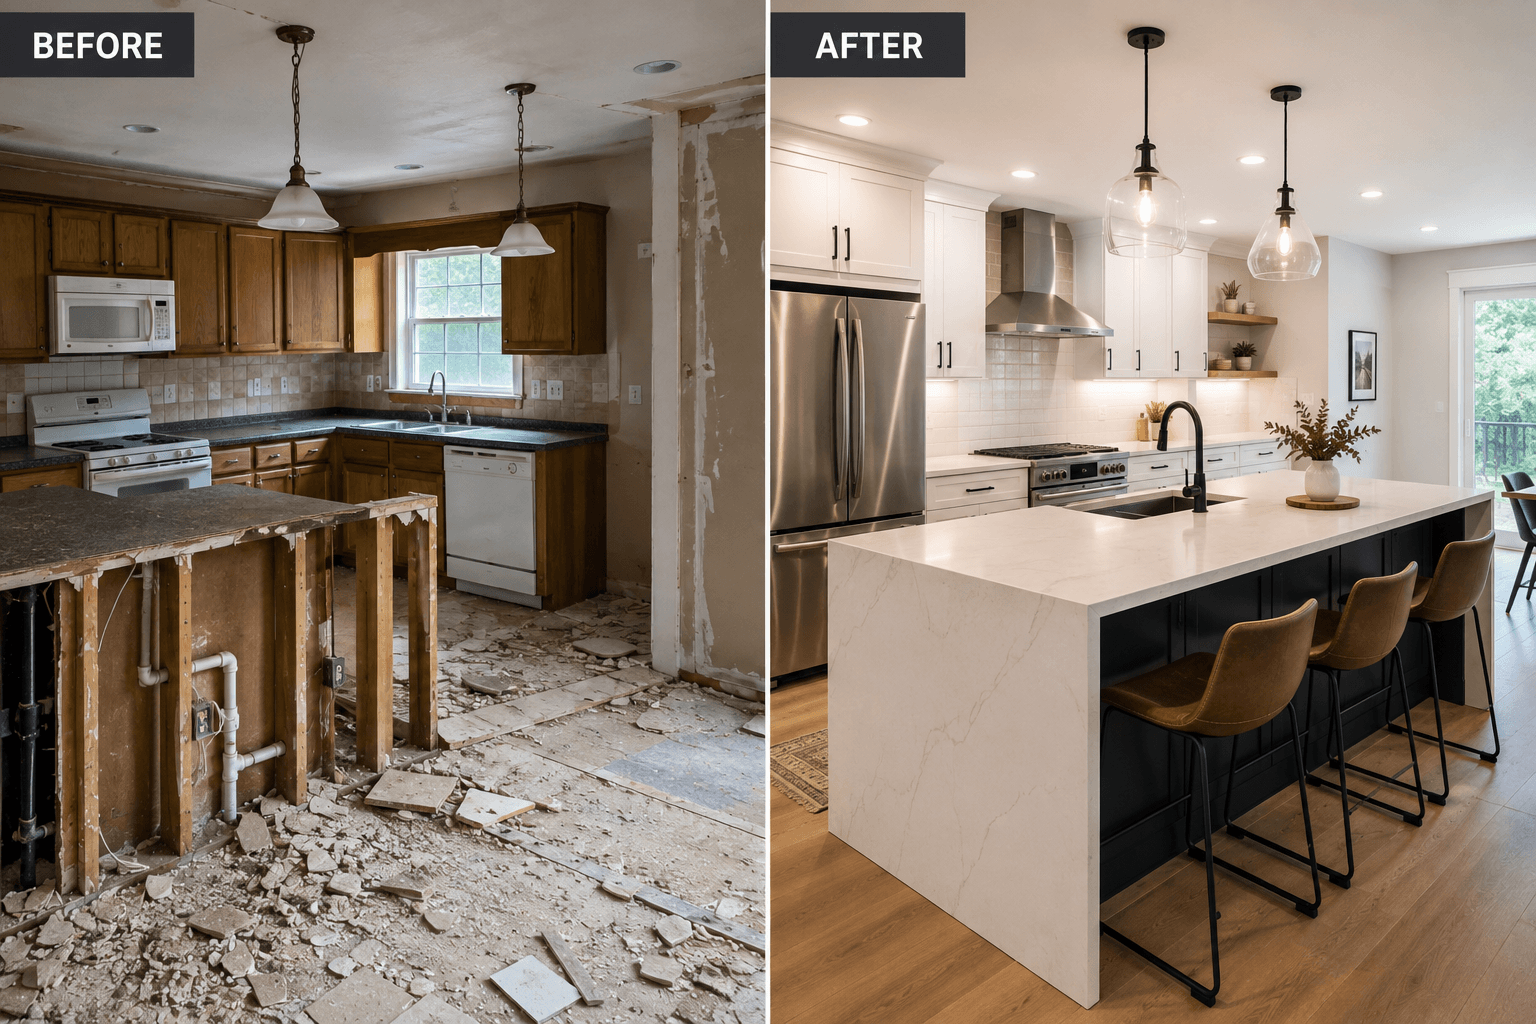
Remodeling contractors work in existing homes and commercial properties where construction activity takes place around finished surfaces, valuable property, customers, and sometimes building occupants. From kitchen and bathroom renovations to additions and whole-home remodels, these projects can create a wide variety of potential risks.
Remodeling contractor insurance can help protect your business against certain risks involving property damage, customer injuries, employee accidents, vehicles, tools, equipment, and other unexpected losses. Whether you're an independent remodeler or operate a company with multiple crews and subcontractors, an insurance program can be tailored around the way your business operates.
The appropriate coverage may depend on the types of remodeling projects you perform, project values, annual revenue, payroll, employees, subcontractor usage, vehicles, equipment, and other factors.
What Insurance Does a Remodeling Contractor Need?
Remodeling contractor insurance generally isn't a single policy. Instead, several types of commercial insurance may be combined to address the different exposures associated with renovation and remodeling work.
General Liability Insurance
Remodeling contractor general liability insurance may help protect your business against certain claims involving bodily injury or property damage arising from your operations.
For example, construction activity could accidentally damage flooring, cabinets, appliances, windows, or another portion of a customer's property. A homeowner or visitor could also be injured around an active work area. Depending on the circumstances and policy terms, general liability insurance may provide coverage for qualifying claims.
Homeowners, commercial property owners, general contractors, lenders, and property managers may also require proof of liability insurance before allowing remodeling work to begin.
Workers' Compensation Insurance
Remodeling employees may encounter power tools, ladders, demolition debris, heavy materials, electrical systems, and other potential jobsite hazards.
Workers' compensation insurance may provide benefits for qualifying employees who experience work-related injuries or illnesses. Requirements can vary depending on the structure of the business and where it operates.
Commercial Auto Insurance
Remodeling contractors frequently use pickup trucks, vans, trailers, and other vehicles to transport employees, building materials, tools, and equipment between projects.
Commercial auto insurance may provide liability and physical damage coverage for qualifying business-owned vehicles. Additional options might be available based on how vehicles are owned and used.
Tools, equipment, and building materials carried in a vehicle may require separate coverage, so these exposures should be discussed with an insurance professional.
Remodeling Tools and Equipment Insurance
Remodelers can have a significant investment in portable tools and construction equipment. Tools and equipment coverage, often provided through inland marine insurance, may help protect qualifying property while it is at a jobsite, being transported, or temporarily stored away from the contractor's primary business location.
Coverage may be available for items such as:
- Power saws
- Nail guns and compressors
- Drills and impact drivers
- Generators
- Sanders and specialty tools
- Ladders and portable scaffolding
- Demolition equipment
- Other portable contractor equipment
Coverage limits, deductibles, and eligible equipment can vary by insurance policy. Larger or particularly valuable equipment may require additional coverage.
Commercial Property Insurance
Remodeling companies that own or lease an office, warehouse, shop, or storage facility may want to consider commercial property insurance.
Depending on the policy, coverage may help protect buildings, office equipment, construction materials, supplies, inventory, and other business property against certain covered losses.
Commercial Umbrella or Excess Liability Insurance
Larger remodeling projects can create the potential for significant liability claims. Some contractors may benefit from additional liability limits beyond those available through their primary policies.
Commercial umbrella or excess liability insurance may provide additional limits above certain underlying insurance policies. Higher limits might also be required by commercial customers, developers, general contractors, or other organizations.
Insurance for Different Types of Remodeling Contractors
Remodeling businesses can perform a broad range of construction services. The specific work performed may influence insurance eligibility, coverage options, and cost.
Insurance options may be available for contractors specializing in:
- Kitchen remodeling
- Bathroom remodeling
- Whole-home renovations
- Home additions
- Basement remodeling
- Interior renovations
- Exterior remodeling
- Tenant improvements
- Commercial renovations
- Residential restoration and improvement projects
Contractors should accurately describe all of the services they perform. Structural modifications, roofing, electrical work, plumbing, excavation, and other specialized operations may require different insurance classifications or additional coverage.
Remodeling Contractors and Existing Property
One of the characteristics that separates remodeling from new construction is that contractors are frequently working around an existing structure and finished property.
A renovation project could involve existing flooring, cabinetry, appliances, windows, furniture, plumbing systems, electrical systems, and other valuable property. Damage to areas outside the contractor's immediate scope of work can potentially result in significant claims.
Contractors should discuss these exposures with their insurance professional and understand how their policies may respond to damage involving existing structures, customer property, and completed work. Coverage can vary depending on the circumstances and policy terms.
Remodeling Contractors and Subcontractors
Many remodeling contractors rely on subcontractors for specialized trades such as electrical, plumbing, HVAC, roofing, drywall, painting, and flooring.
Insurance companies may have specific requirements regarding subcontracted work. Contractors may need to obtain certificates of insurance from subcontractors and verify that appropriate coverage is maintained.
Written subcontractor agreements and additional insured requirements may also be appropriate depending on the project. The amount and type of work performed by subcontractors should be accurately disclosed when obtaining remodeling contractor insurance.
Builders Risk Insurance for Remodeling Projects
Larger renovations and additions may create a need for builders risk insurance. Depending on the policy and project, builders risk coverage may help protect a structure under renovation along with certain construction materials and supplies.
Coverage for remodeling projects can be more complicated than coverage for new construction because an existing structure is already present. The property owner, contractor, lender, or another party may be responsible for arranging appropriate coverage.
Responsibility for builders risk insurance should generally be determined before a significant renovation project begins.
Protect Your Remodeling Business
A remodeling company can represent a substantial investment in employees, subcontractor relationships, vehicles, tools, equipment, and professional reputation. Appropriate business insurance can help provide financial protection when certain unexpected accidents or losses occur.
The insurance needs of a small residential remodeler may be very different from those of a larger renovation contractor managing multiple crews and subcontractors. Project size, annual revenue, payroll, subcontractor costs, vehicles, equipment values, claims history, and the types of work performed can all influence coverage needs and pricing.
Working with an independent insurance agent can provide access to multiple insurance companies and coverage options, helping you find an insurance program appropriate for your remodeling business.
FAQs
What insurance does a remodeling contractor need?
A remodeling contractor's insurance program may include general liability, workers' compensation, commercial auto, tools and equipment, and commercial property insurance. Builders risk, umbrella or excess liability, and other specialized coverage may also be appropriate depending on the projects performed.
Does remodeling contractor insurance cover damage to a customer's home?
General liability insurance may provide coverage for certain qualifying property damage claims arising from remodeling operations. Coverage can depend on what was damaged, how the damage occurred, whether the property was part of the contractor's work, and the terms, conditions, limits, and exclusions of the policy.
Do remodeling contractors need insurance for subcontractors?
Subcontractors generally should maintain their own appropriate insurance. Remodeling contractors may need to collect certificates of insurance, establish minimum coverage requirements, and use written subcontractor agreements. Specific requirements can vary by insurance company and project.
How much does remodeling contractor insurance cost?
The cost of remodeling contractor insurance can vary based on annual revenue, payroll, project size, services performed, subcontractor costs, vehicles, equipment values, claims history, and selected coverage limits. Comparing options from multiple insurance companies can help identify coverage appropriate for the business.